Medcore Brokerage places group critical illness, cancer and hospital indemnity coverage for employers across Texas and Oklahoma. We are a broker, not a carrier: we quote the supplemental lines against your existing medical plan, show you what each structure costs your company, and handle the enrollment in English and Spanish.
What critical illness insurance does for your employees
A critical illness plan pays a lump sum in cash directly to the employee on diagnosis of a covered condition — commonly heart attack, stroke, cancer, organ failure, end-stage renal disease. The money is not tied to medical bills. Employees use it for the deductible, the out-of-network specialist, the mortgage, or the drive to Houston for treatment. That is the gap it fills: your medical plan pays providers, this pays the household.
Who pays the premium
Three structures, and the choice drives both cost and participation:
- Employer-paid. The company buys a base benefit amount for every eligible employee. Highest participation, and it is the version employees notice at open enrollment. Cost depends on the benefit amount you choose and your census, which is what we quote.
- Voluntary (employee-paid). Offered through your plan, paid by payroll deduction. No premium cost to the employer; the employer’s contribution is the group rate itself and the payroll setup.
- Split or buy-up. Employer funds a base amount, employees buy additional coverage for themselves and dependents. This is the most common structure we place for 50-to-200-employee groups.
Why the group rate beats an individual policy
Group critical illness is priced for the whole census, usually with simplified or guaranteed issue at the plan’s participation threshold, so employees who could not pass individual underwriting are covered. There is no medical exam in most group offerings, the rate is level for the plan year, and the coverage is portable in many contracts. An employee shopping the same benefit alone is individually underwritten and pays retail. We will show you both numbers side by side for your own group.
Hospital indemnity and cancer plans: the companion lines
Employers rarely buy critical illness alone. Hospital indemnity pays a fixed amount per admission and per day; a cancer plan pays scheduled benefits across diagnosis, treatment and recovery. Stacked with a high-deductible medical plan, the three together cover the cash shortfall a deductible leaves behind. We quote them as a package so you can see what each one adds.
Adding coverage at renewal, or mid-year
The clean point of entry is your renewal, alongside the medical plan, in one enrollment. Mid-year additions are possible for most carriers and usually need a participation minimum and a short enrollment window. If your renewal is inside the next 90 days, that is the conversation to have now.
What we do as your broker
Five things, on every supplemental placement we run:
- Quote the supplemental lines across carriers. Critical illness, hospital indemnity and cancer, priced against your census rather than a rate card.
- Model employer-paid against voluntary. Same benefit amounts, both funding structures, so you can see what each one costs the company.
- Check the design against your medical deductible. The benefit has to land where the gap actually is, not where the brochure says it is.
- Run the enrollment, bilingual. English and Spanish, alongside the medical plan in one sitting.
- Service the claims questions that follow. Your HR team should not be the first call when an employee files.
We do this for Texas and Oklahoma employers, most of them between 50 and 200 employees.
Not sure whether you’re overpaying for benefits? Get a free Benefits Cost Review — we benchmark your current plan, contributions and claims data against comparable Texas and Oklahoma employers. No obligation.
Frequently asked questions
Does the employer or the employee pay for critical illness insurance?
Either, and both are common. Employer-paid buys a base benefit for everyone; voluntary is payroll-deducted at group rates and costs the employer nothing in premium. Many Texas employers fund a base amount and let employees buy up.
Is employer-provided critical illness insurance cheaper than an individual plan?
Generally yes for the employee, because the group is rated as a whole and issue is simplified or guaranteed at the participation threshold, with no medical exam in most offerings.
What types of critical illness plans do employers offer?
Lump-sum plans by covered condition, tiered plans that pay a percentage by severity, and cancer-specific or hospital indemnity plans used alongside. Benefit amounts are usually set in bands per employee, with spouse and child riders.
Can we add critical illness coverage in the middle of the plan year?
Usually. Most carriers allow a mid-year addition with a participation minimum and a defined enrollment window. Renewal is simpler.
Do you work with employers outside Texas?
We serve US employers, concentrated in Texas and Oklahoma.
Related coverage and next steps
- Cost detail: How Much Does Critical Illness Insurance Cost for Employees
- How to add it: How to Offer Critical Insurance Cover to Employees
- Where to buy: Where to Find Critical Illness and Cancer Insurance for Your Business
- Product pages: Critical Illness Insurance, Hospital Indemnity Insurance, Cancer Insurance
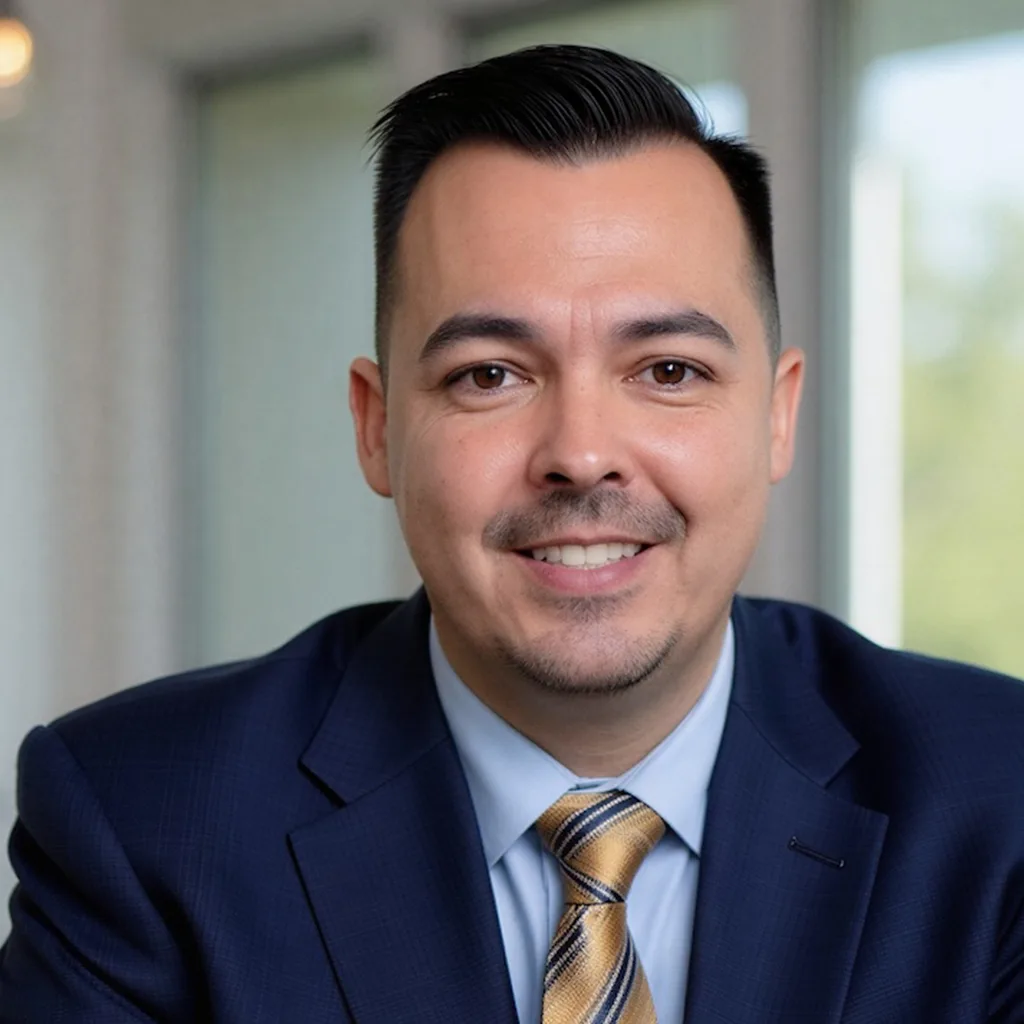
Written by
Trey Driver
President of Medcore Brokerage in McKinney, Texas. Licensed in Texas and Oklahoma (TX General Lines Agent #1797664), helping Texas employers with 50 or more employees design and run their benefits since 2012.